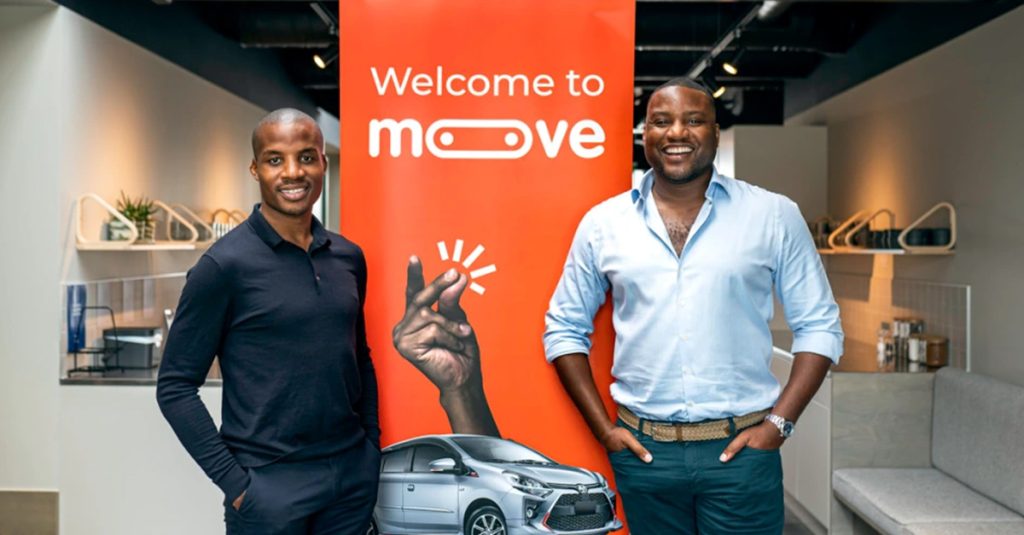
Moove’s latest funding round makes its evolution difficult to miss. The company that began by financing vehicles for ride-hailing drivers in Africa has raised $250 million at a $2.1 billion valuation to build what it calls infrastructure for autonomous mobility.
The August 2026 financing is not simply a larger version of the original lending model. Moove now operates across 11 cities and has a partnership with Waymo in the United States, pushing the company closer to fleet operations, charging, servicing and asset management for autonomous vehicles.
Yet the core idea is recognisable from its African beginnings: mobility platforms need somebody to finance, own and operate the physical assets underneath the software.
The first product was access to the vehicle
Ride-hailing created work opportunities for drivers across African cities, but many potential drivers could not afford the car required to participate. Traditional lenders often struggled to underwrite workers whose income depended on platform activity rather than a fixed salary.
Moove built around that mismatch. It used mobility data and revenue-linked repayment structures to finance vehicles for drivers, effectively turning platform earnings into part of the underwriting model.
That was a local financial-services problem, but it created capabilities with wider value. Moove had to understand vehicle acquisition, maintenance, insurance, utilisation, collections and residual value. Those are operational disciplines, not just lending features.
As the company expanded into cities including London, Dubai, Cairo, Hyderabad and Bangalore, those capabilities became portable.
Autonomous fleets need the same boring infrastructure
Autonomous vehicles change who drives the car, but they do not eliminate the need to own, charge, clean, repair, insure and deploy fleets efficiently.
That is the bridge between Moove’s old model and its new one.
The company describes its current strategy as a global infrastructure layer for mobility and autonomous fleets. Its investor materials show operations across Africa, Europe, the Middle East and Asia, with further expansion planned.
A partnership with Waymo gives that thesis a higher-stakes test. Autonomous vehicle companies are technically sophisticated, but operating a commercial fleet at city scale still requires mundane logistics. A specialist that can manage those assets well becomes part of the infrastructure, even if it did not build the driving software.
Capital intensity remains the central risk
Moove’s model is attractive because transport assets generate revenue. It is also difficult because those assets are expensive.
Fleet businesses need large amounts of capital before revenue arrives. Vehicles depreciate, maintenance costs vary and utilisation can fall if demand changes. Geographic expansion introduces different regulations, insurance markets and vehicle economics.
The $250 million round gives Moove more capacity to absorb that complexity, but funding size is not the same as operating leverage. The company still has to prove that each additional fleet can produce returns after financing costs and local operating expenses.
Its $2.1 billion valuation therefore reflects a bet on execution as much as on market size.
Why it matters
African startups are often told to build locally and then export software because software crosses borders more easily than physical operations. Moove is testing a harder version of that path.
It exported an operating model built around an African constraint: people had demand for mobility work but lacked affordable access to vehicles. Solving that problem required finance, data and fleet operations together.
Those capabilities now have value in markets with very different income levels because the underlying question is similar: who will own and manage the vehicle fleet required by a mobility network?
That makes Moove notable beyond its valuation. It is evidence that an African company’s operational knowledge can travel, even when the product includes heavy physical assets.
What to watch
The Waymo relationship is the most important proof point. Watch how much of Moove’s revenue and fleet growth comes from autonomous mobility versus driver-focused financing, and whether margins improve as the business handles larger institutional fleets.
Expansion also deserves scrutiny. Moove lists Kampala and Mumbai among upcoming markets, which will test whether it can standardise fleet operations without losing local discipline.
The company started by asking how to put more drivers behind the wheel. Its next phase is asking who runs the fleet when the driver eventually disappears.