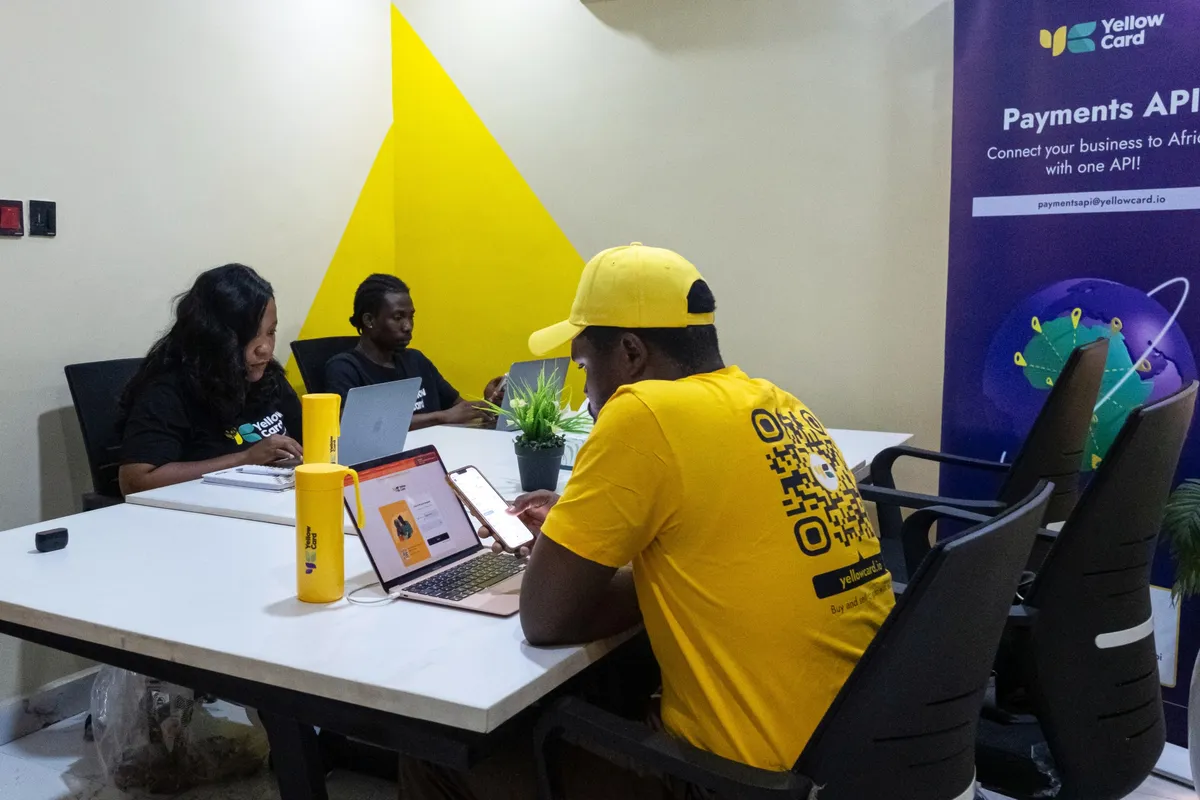
Yellow Card’s African expansion is increasingly visible in a less glamorous place than its trading interface: the licences, registrations and banking permissions behind the product.
The company’s regulatory register, updated in August, lists a patchwork of approvals across markets including South Africa, Zambia, Botswana, Ghana and Nigeria. The details differ by country because there is no single African crypto licence. A platform that wants broad coverage has to assemble compliance market by market.
That process is becoming part of the competitive product. For institutional customers moving stablecoins across borders, the question is no longer only whether the rail works. It is whether the provider can explain who regulates it, how money enters and leaves the system, and what happens when local rules change.
Regulation is becoming operational infrastructure
Yellow Card’s South African entity is authorised as a Category I financial services provider for crypto assets. The company also says it operates as a third-party payments provider under sponsorship arrangements with Standard Bank and Nedbank.
In Zambia, the relevant entity was registered as a virtual asset service provider in March 2026. Ghana appears through a VASP registration, while other markets use different financial-intelligence or payments frameworks.
Nigeria illustrates why the wording matters. The Securities and Exchange Commission announced in August that Yellow Card was among firms cleared for the Accelerated Regulatory Incubation Programme. That is approval in principle within an incubation framework, not a full unrestricted licence. Yellow Card has itself stressed the distinction.
For a crypto company, getting those distinctions right is part of trust. Overstating regulatory status can damage the same credibility that licences are meant to build.
Stablecoin infrastructure raises the bar
Yellow Card increasingly presents itself as infrastructure for businesses rather than simply a retail exchange. Its API supports local bank and mobile-money rails, foreign exchange, customer verification and crypto settlement.
That shifts the compliance burden. A consumer trading app may be responsible mainly for its own customers and transactions. An API provider can sit inside the payment flow of other companies, which means its controls become part of someone else’s product risk.
Enterprise clients will ask questions that consumers rarely do: Which legal entity holds the relationship? Where are funds settled? What customer checks are required? What reporting obligations apply? Can a payment corridor remain available if one regulator changes its rules?
The companies that answer those questions consistently can turn compliance into a sales advantage.
The moat is expensive to build
A multi-country licence footprint requires legal teams, reporting systems, banking relationships and local entities. It also requires patience because regulation moves at different speeds.
That cost can frustrate expansion, but it can also protect established operators. A new entrant may be able to reproduce an application quickly. Rebuilding years of regulatory relationships is harder.
This is one reason the African crypto market is maturing away from the pure “access” narrative. The earliest wave competed on whether people could buy or sell digital assets at all. The next wave has to prove that businesses can rely on the infrastructure repeatedly and legally.
Why it matters
Stablecoins are moving closer to ordinary payment and treasury use. As that happens, crypto companies are being judged more like financial infrastructure providers.
Yellow Card’s regulatory expansion shows what that transition looks like in practice. The work is fragmented, jurisdiction-specific and often invisible to users, but it determines whether banks and enterprises are comfortable building on the platform.
For African fintech, this is healthy pressure. Compliance should not be treated as a marketing badge or a final step after growth. It is part of the architecture of a product that moves money.
What to watch
Watch for full licences where Yellow Card currently operates under registrations, sandboxes or approvals in principle. Nigeria is particularly important because the SEC’s incubation process is still distinct from final licensing.
Also watch banking and settlement partnerships. Regulatory permission has more commercial value when a platform can reliably connect stablecoin rails to local fiat accounts and mobile money.
The broader signal is that trust is becoming measurable. In African crypto, the licence page is starting to matter almost as much as the product page.