Direct-to-device satellite connectivity has moved from an African future scenario to an operating service. Airtel Africa launched a commercial satellite-to-mobile service in the Democratic Republic of the Congo in August, allowing compatible standard smartphones to use basic services outside terrestrial network coverage.
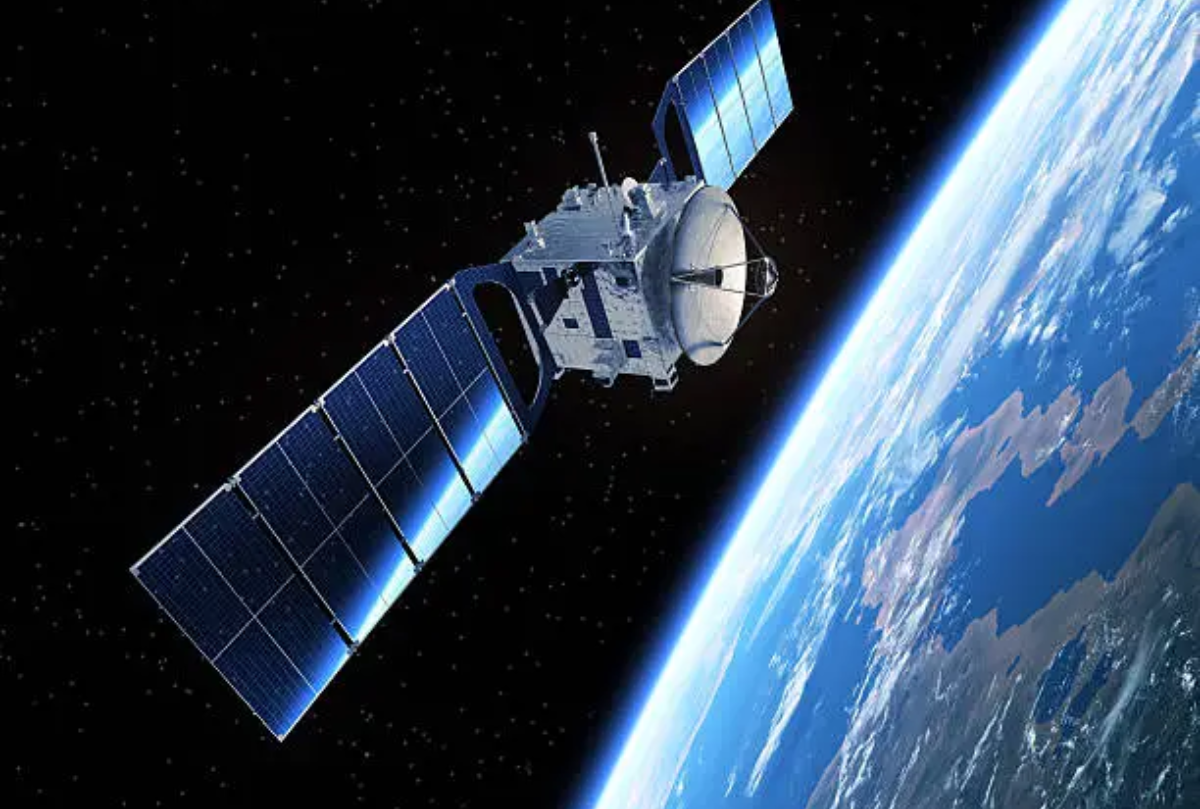
That shift matters because direct-to-device, or D2D, does not require the user to install a satellite dish. The satellite behaves more like a cell tower in space, connecting to an ordinary handset over supported mobile spectrum and technology.
ITWeb Africa reported on October 23 that only 13% of mobile operators in sub-Saharan Africa had satellite partnerships in the GSMA Intelligence Satellite and NTN tracker for the third quarter of 2026, below a 19% global average. Commercial deployments are nevertheless beginning to change the competitive map.
The first product is coverage, not broadband
D2D can sound more capable than today’s services actually are. Early deployments are generally suited to lightweight communications such as SMS and text messaging rather than full high-speed mobile broadband.
In the DRC, Airtel Africa’s Starlink Mobile service supports light-data applications on compatible LTE Android smartphones, with Apple support expected later. ITWeb Africa’s August report said customers need an active data bundle or roaming enabled.
That still solves a meaningful problem. A message that works outside tower coverage can matter to a traveller, farmer, field worker, emergency responder or remote community even if the connection cannot yet stream video.
The near-term product is therefore continuity of basic communication.
Operators have a reason to partner instead of resist
D2D creates an unusual competitive relationship. Satellite companies can extend coverage into places where a mobile operator has no tower, but they still benefit from spectrum access, billing relationships and subscribers held by local operators.
Partnership allows a telco to present satellite coverage as an extension of its own network rather than a substitute for it. That can protect the operator’s customer relationship while reducing the capital required to build terrestrial infrastructure into low-density areas.
The alternative is a harder regulatory and commercial contest over whether a satellite provider can serve local users directly and under what licence.
Africa is likely to see both models.
Spectrum makes this a policy story
D2D is not just an engineering upgrade. A satellite service transmitting to ordinary phones interacts with national spectrum assignments and telecom licensing.
Regulators must decide how satellite capacity can use mobile frequencies, how interference is managed, whether existing licensees must consent and what consumer, security and tax obligations apply. Those questions become especially sensitive when a foreign satellite network reaches users across national borders.
The dispute around Starlink’s fixed service in Senegal, while not itself a D2D case, shows the broader tension between rapid coverage expansion and national control over communications markets.
For D2D to scale, operators and satellite providers will need regulatory structures that are predictable enough to support multi-country deployments.
The economics may redraw the edge of the network
Mobile networks are built around density. Towers are easiest to justify where enough users or enterprise customers can support the investment.
D2D changes the marginal cost of covering the last, sparsely populated areas because the satellite is already passing overhead. It does not eliminate terrestrial networks, which remain better suited to dense traffic and high-capacity demand. Instead, it can redefine what counts as “covered” at the edge.
That creates a layered network: fibre and towers carry heavy traffic where economics support them, while satellite fills some of the gaps and provides backup.
Why it matters
Africa has some of the world’s hardest coverage economics across remote, low-density and geographically difficult areas. D2D offers a way to improve basic reach without waiting for a tower in every location.
For operators, it can become a retention tool and a coverage extension. For satellite companies, operator partnerships provide distribution and spectrum access. For regulators, it creates a new category that cuts across satellite and mobile rules.
The biggest mistake would be to treat it as a simple replacement technology. Its value is likely to come from how it complements existing networks.
What to watch
The first markers are service capability, handset support, pricing and regulatory approvals. Watch whether African D2D services move from messaging to voice and broader data, and how quickly iPhone and lower-cost Android compatibility expands.
Also watch partnership concentration. If a small number of satellite networks sign multiple major operator groups, the bargaining power and infrastructure choices of African telcos could shift quickly before the decade ends.