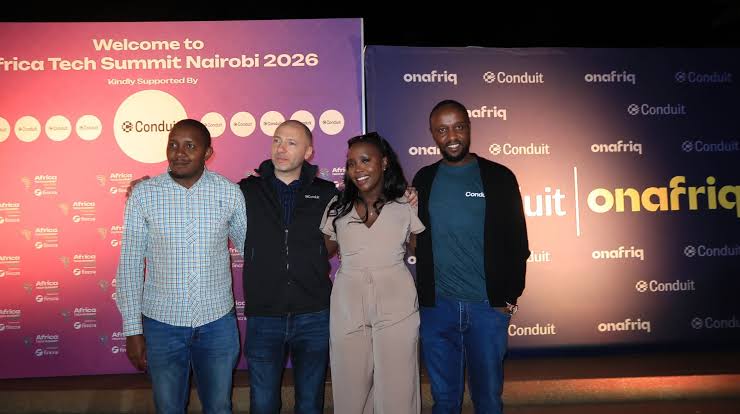
Onafriq is putting stablecoins into the part of cross-border payments that customers rarely see: treasury, liquidity movement and settlement.
In July, the pan-African payments company disclosed a partnership with Privy to build programmable wallet infrastructure for stablecoin workflows. The first use cases are not a new retail wallet or a token product pitched to consumers. They are operational tasks inside a payment network: moving liquidity, managing treasury positions and settling value across borders.
That choice says something important about where stablecoins may become useful in African finance. The strongest near-term case may be behind the scenes, where payment companies already spend time and money moving funds between currencies, entities and markets.
Start with the plumbing
Onafriq sits between banks, mobile-money operators, merchants and enterprises. Privy says the network connects more than one billion mobile-money wallets and 500 million bank accounts across 43 African markets. Onafriq’s own company profile describes a network spanning dozens of countries and more than 1,300 payment corridors.
At that scale, cross-border payments are not only about the instruction to send money. They are also about where liquidity sits, when prefunding is required, how quickly counterparties can rebalance and how settlement is reconciled.
Stablecoins can shorten some of those loops because a digital dollar-denominated asset can move outside traditional banking windows. That does not remove foreign-exchange rules, licensing obligations or the need to redeem into local currency. It can, however, give a regulated payment company another rail for moving value between its own operating points.
Onafriq’s approach is therefore more conservative than the usual crypto pitch. The company is inserting the technology into an existing payments network instead of asking African users to adopt a new financial identity.
Treasury is where the economics become visible
Cross-border payment businesses can look simple at the user interface while being complex underneath. A payment may originate in one currency, terminate in another and pass through entities that each have their own liquidity requirements.
The result is trapped capital, prefunding and operational coordination. A treasury team may need to keep balances in several places just to guarantee that payments clear when customers expect them to.
Privy’s case study says Onafriq is using programmable wallets for cross-chain stablecoin transfers, treasury management and settlement. The rollout is phased and remains subject to regulation in each market. That caveat matters. Stablecoins do not create a regulatory shortcut, especially for a network that touches licensed banks and mobile-money systems.
But if the technology can reduce the amount of idle liquidity required to support a corridor, it has a measurable business case. The value is not that a transaction contains crypto. The value is that treasury can move money with less friction.
Why it matters
Africa’s cross-border payment problem is often described as a user-experience problem. It is also a balance-sheet problem.
Payment providers need enough liquidity in the right markets, at the right time, while complying with local currency and settlement rules. That is one reason cross-border expansion can become expensive even when customer demand is obvious.
Onafriq’s stablecoin work is worth watching because it puts the technology against that constraint. If stablecoins become useful treasury instruments for regulated payment networks, adoption could grow without requiring ordinary customers to hold them directly.
That would also change the competitive question. The winners would not necessarily be the companies with the loudest crypto brands. They could be the networks that quietly use digital assets to make existing payments faster, cheaper and easier to fund.
What to watch
The first test is whether Onafriq moves from internal treasury and settlement workflows into live, repeatable corridors at meaningful volume. The second is regulation: each market will determine how stablecoin-backed settlement interacts with foreign exchange, payments licensing and reporting.
Watch, too, for evidence on prefunding and settlement time. Those metrics will show whether the technology improves the economics or simply adds another technical layer.
The larger signal is already clear. In African payments, the next serious stablecoin story may begin in treasury operations rather than in a consumer wallet.