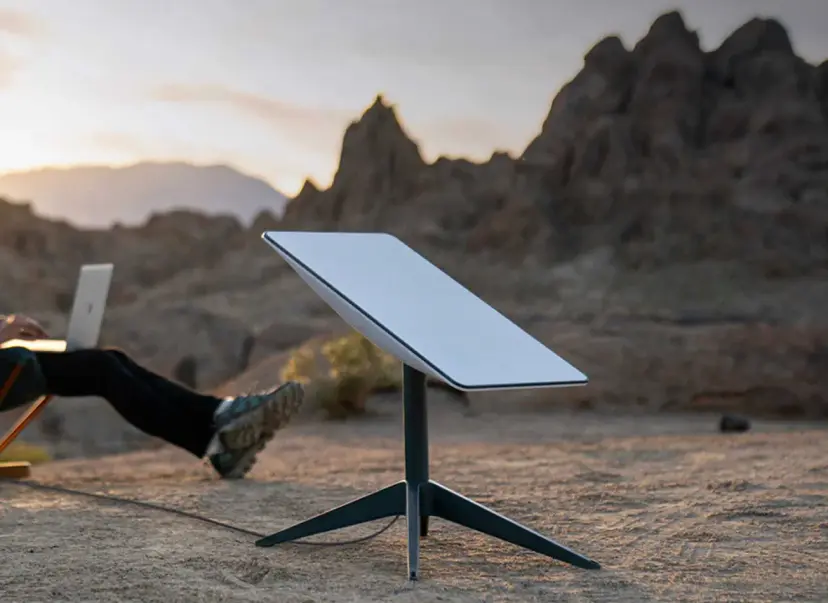
MTN Uganda has taken its Starlink partnership one step further by launching MTN Starlink for Business, a managed connectivity offer aimed at companies and institutions that operate beyond the practical reach of fibre and conventional mobile infrastructure.
The company says the service combines Starlink’s low-Earth-orbit satellite capacity with MTN’s local support and enterprise portfolio. At a launch demonstration at Libra International School in Zirobwe, MTN positioned the product for primary connectivity, backup links and rapid deployment in places where laying terrestrial infrastructure is slow or uneconomic. MTN Uganda’s launch statement was published on October 24.
That packaging is the important part. Satellite internet is no longer being presented only as a direct-to-consumer alternative. In Uganda, MTN is trying to make it one component of an enterprise connectivity stack.
The product is really about service integration
MTN and Starlink first announced their Uganda partnership in August, saying satellite capacity would be used to extend connectivity to remote and underserved enterprise customers. The initial target sectors included education, healthcare, agriculture, humanitarian response, energy, tourism, financial services and government services. MTN described the satellite layer as complementary to its terrestrial network rather than a replacement for it.
The October launch makes that logic more concrete. An enterprise customer can buy satellite connectivity through a local operator that already has account management, support teams, billing relationships and network services in the market.
For a school, lodge, farm, health facility or branch office, that can matter more than the underlying orbit. A satellite terminal solves only one part of the problem. Organisations still need installation, network configuration, support, failover planning and someone accountable when the link stops working.
MTN is protecting its place in the connectivity chain
Starlink has changed the competitive geometry of African broadband because it can reach customers without waiting for a local fibre build. Mobile operators therefore have two broad choices: treat satellite providers as external competitors or integrate them into their own product portfolios.
MTN Uganda is choosing integration.
That approach protects the operator’s relationship with business customers while giving those customers another access technology. It also lets MTN use satellite links selectively. A remote site may use Starlink as its main connection, while a city office remains on fibre and another branch uses mobile broadband. The enterprise account can still sit with one provider.
This is a more defensible model than pretending every location should be served by the same network architecture.
Remote connectivity is becoming a portfolio problem
Uganda still has locations where conventional deployment is expensive relative to the number of users or the revenue available from a site. Satellite can change the economics of those specific locations, but it does not remove the need for terrestrial investment in dense areas.
That distinction matters. Low-Earth-orbit systems are particularly useful where distance, terrain or sparse demand makes fibre or tower expansion difficult. They are less likely to replace high-capacity terrestrial networks in places where those networks already work well.
For enterprises, the more useful question is therefore not “satellite or fibre?” It is which mix of fibre, mobile and satellite gives each site the reliability, capacity and recovery path it needs.
Why it matters
The African satellite story is moving from access technology to distribution model. Operators that can combine satellite capacity with local service, support and existing enterprise relationships may be able to absorb the technology into their businesses rather than lose customers to it.
MTN Uganda’s launch also gives Starlink a route into organisations that may prefer buying connectivity from a regulated local operator they already know. That could widen adoption in sectors where procurement, support and accountability matter as much as raw speed.
For other mobile operators, the lesson is straightforward: satellite connectivity is becoming a product layer that can be bundled, managed and sold alongside terrestrial networks.
What to watch
The next test is commercial, not promotional. MTN has not publicly disclosed the price structure, service-level commitments or number of enterprise sites expected to use the offer. Those details will determine whether the service becomes a niche resilience tool or a meaningful part of Uganda’s business-connectivity market.
Watch how quickly MTN expands deployments outside demonstration sites, whether customers use Starlink mainly as primary or backup connectivity, and whether the same managed model appears across more MTN markets.